Don’t Simply Retire. Retire with Kai-Zen®

Chante Denis • August 26, 2025

The 5-Year Retirement Plan

Retirement isn’t merely the end of your career—it’s a milestone meant to herald a more fulfilling, secure, and prosperous stage of life. The key? Transition from merely retiring to something great—not just from something. New definition of retirement; time freedom, moving from what you have to do towards doing what you want to do.


One Strategy, Exponentially Stronger Outcomes


Enter Kai-Zen®, an innovative retirement strategy developed by NIW Corp. that lets you supercharge your savings using leverage—giving you up to 3x more money to fund a unique cash-accumulating insurance policy.


Coupling your contributions with selective bank financing, Kai-Zen unlocks the potential for accelerated growth while providing the protections inherent in life insurance, including death and living benefits.


Why Kai-Zen Stands Out:


1. Maximized Retirement Savings via Leverage

High-income earners can pair personal savings with institutional financing—multiplying capital at work in your policy. It’s a strategic boost beyond traditional retirement vehicles.


2. Tax-Advantaged Growth and Withdrawals

Built on an indexed universal life (IUL) insurance structure, Kai-Zen’s cash value grows tax-deferred. Later, you can access this value through policy loans or withdrawals, often tax-free—providing flexible income in retirement.


3. Protection from Market Fluctuations

The IUL portion allows upside market participation without downside exposure—offering upside potential while preserving principal through downturns.


4. Built-In Safety Nets

Banks lend against the policy’s cash value—no personal guarantee required. Loans are repaid from within the policy itself, limiting your liability.


5. Resilience in Rising Interest Rate Environments

While increased interest can pressure financing, Kai-Zen is structured with built-in safeguards—designed to perform even when borrowing costs rise.


6. Credit, Clarity & Compliance for Institutional Partners

Banks favor Kai-Zen due to transparent policy structure, secure collateral, and consistent administration—making it a stable and scalable financing option.


What the Kai-Zen Strategy Looks Like in Practice


According to Insurance & Estates, the premium financing often proceeds in phases—your contributions may fund the policy initially (years 1–5), followed by bank 3:1 leverage in the next phase, compounding growth through year 15 and beyond.


"Safe Money Lady" outlines the core approach:


Establish a high-cash-value IUL policy,


Use bank matching for contributions,


Benefit from protected growth, and


Extract income later via tax-free policy loans.


Who Stands to Benefit Most

Kai-Zen is ideal for:


  1. High-net-worth professionals and executives seeking powerful, tax-efficient retirement vehicles.
  2. Those maximizing retirement income beyond traditional limits.
  3. Individuals looking for a flexible, protected, and tax-smart liquidity strategy.
  4. People who can commit to funding early years but want control and growth access later.
  5. Smart, Strategic, Sophisticated


Required Qualifications:

  • Your combined household income is at least 100k per year.
  • You are between the ages of 18 - 65.
  • You are in average or good health.
  • You can contribute a minimum of $22k per year.


Why Kai-Zen®

We have all used leverage to purchase a nicer house or to buy a better car. Kai-Zen uses leverage for the potential to accumulate more growth & obtain more protection, while providing the ability to maintain your current standard of living. That’s the smart way to use leverage.


Kai-Zen isn’t just another financial product—it’s a forward-thinking, disciplined, and highly structured system designed to deliver powerful results, tax efficiency, and protection simultaneously. Perfect for employee retention and attraction.

---


Ready to Make Kai-Zen Work for You?


Let’s explore whether Kai-Zen aligns with your retirement vision. Schedule your complimentary consultation now with Master Wealth Builders:


➡ Book Your Free Consultation

Step into a retirement that doesn’t just sustain—but elevates.

---


If you’d like to dive deeper into illustrations, risk scenarios, or compare this with traditional retirement options, just let me know—I’ll be happy to help.


To your success,

TK Pryor

Wealth Strategist | Master Wealth Builders

Share...

Calculator, eyeglasses, pen, and chart papers on a desk with a plant
September 30, 2026
Learn how to calculate your net worth using a simple assets-minus- liabilities formula. See two examples, common mistakes, tracking tips, and free online calculators.
Nested money-supply layers showing cash, bank deposits,
and institutional near-money assets.
By Chante Denis • September 29, 2026
What is the difference between M2 and M3 money supply? Learn what each includes, how liquidity works, how Fed QE and QT affect financial conditions, why the Fed stopped publishing M, and how the ECB defines M.
Jasmine Rush
By Chante Denis • September 28, 2026
Meet Jasmine Rush, the Navy veteran behind Speaking From the Lens, Mission to Momentum, and Speaking Beyond the Lens—businesses built around storytelling, strategy, advocacy, and legacy.
By Manus AI • September 16, 2026
Compare public, private, permissioned, consortium, and hybrid blockchains across access, privacy, security, governance, cost, scalability, and use cases. Learn which architecture fits your organization.
When you deposit money into your bank account, have you ever wondered: Is my money just sitting...
By Chante Denis • January 22, 2026
Learn what fractional reserve banking is, how it works, and why it matters—explained in plain English with simple examples.
FIA returns explained
By Chante Denis • October 1, 2025
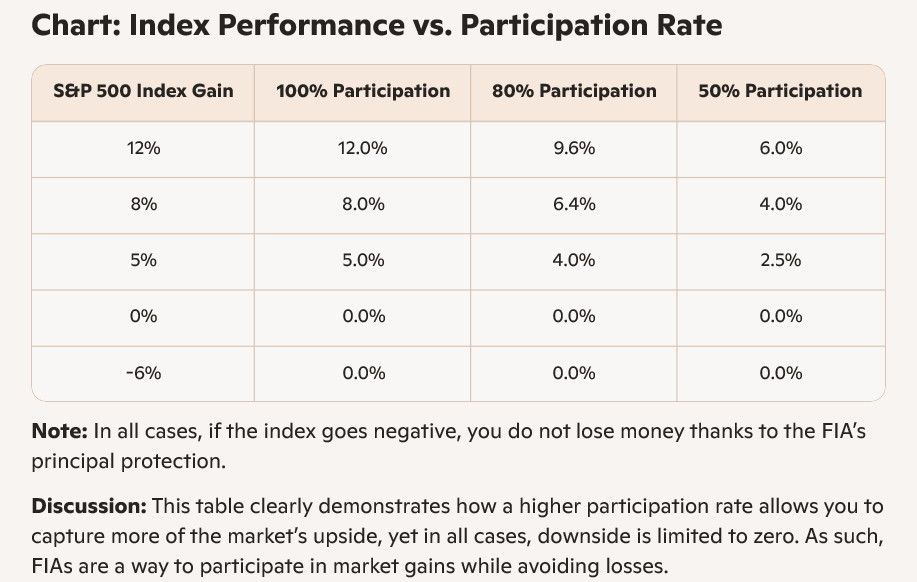
Key Takeaways - The participation rate determines how much of the index’s positive return your FIA credits you each year. - A higher participation rate means more upside growth, but it’s always paired with downside protection—your principal never shrinks due to market losses.
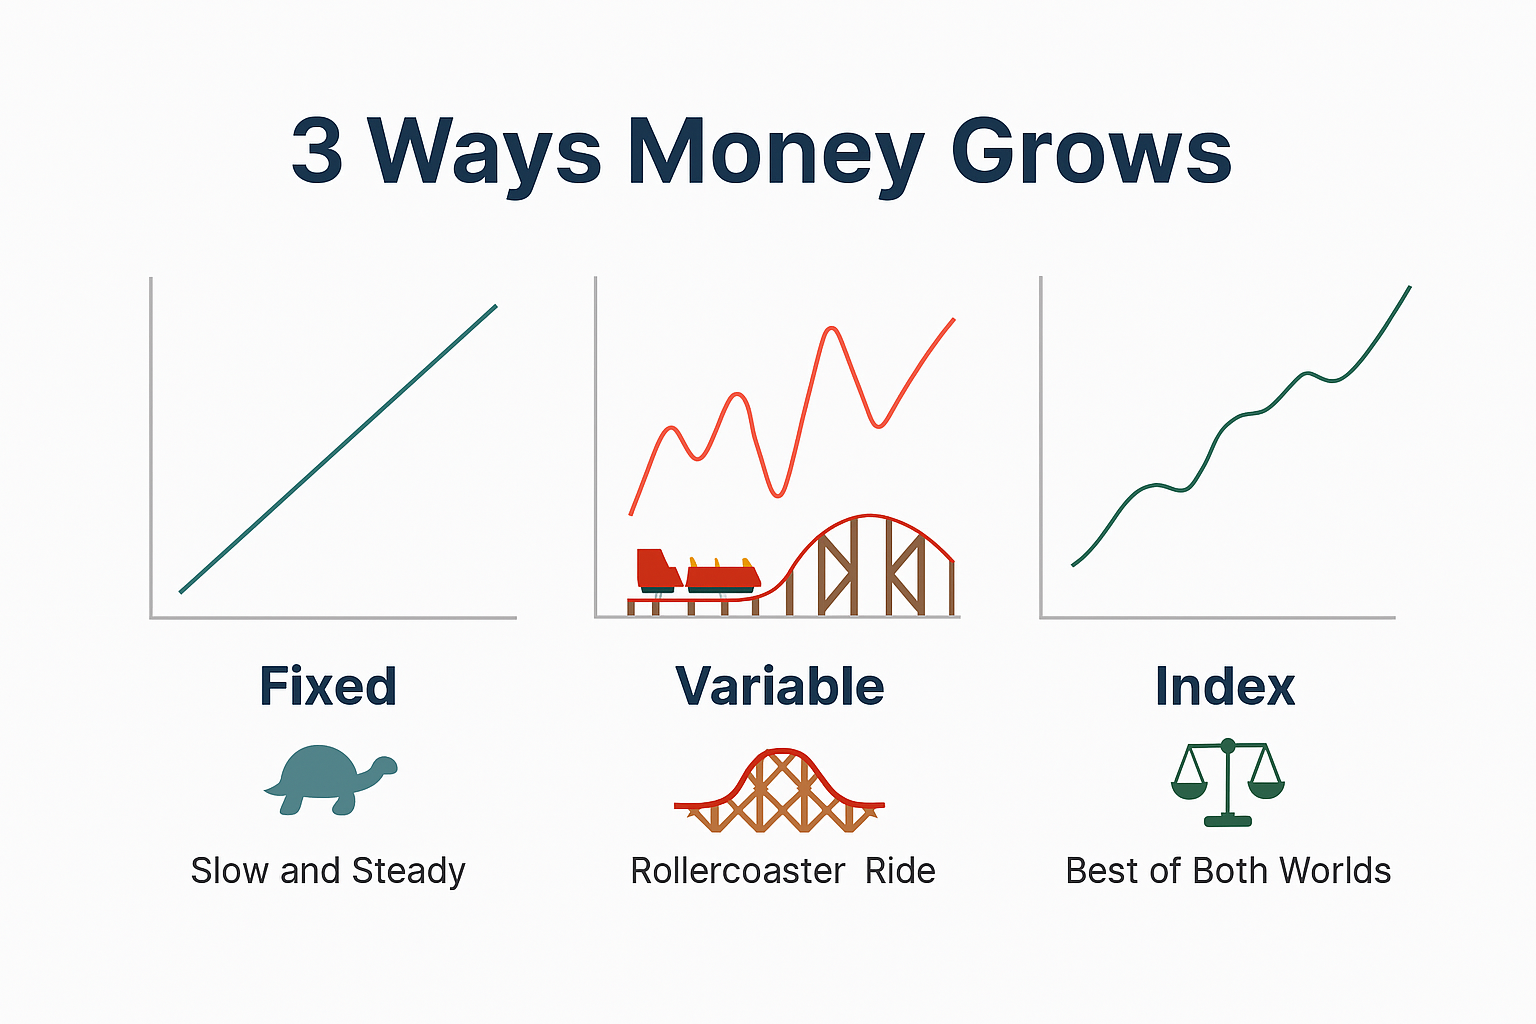
You earn when the market goes up, but you’re protected from losses when the market goes down.
By Chante Denis • September 28, 2025
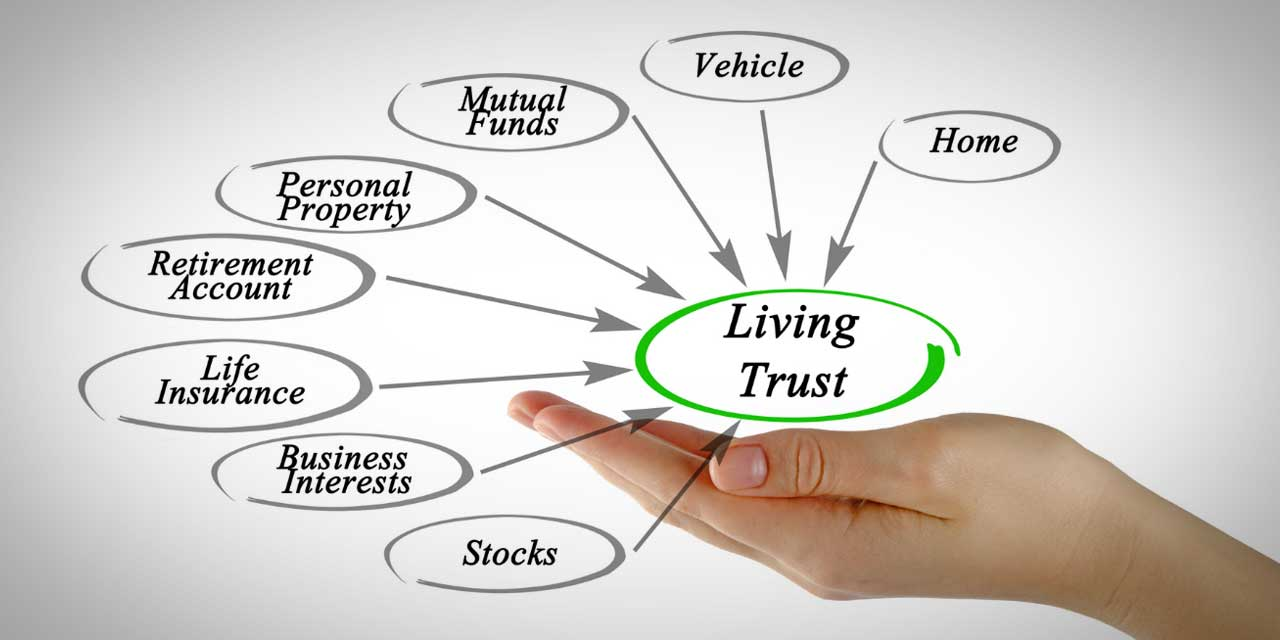
Imagine you’re climbing a mountain. With stocks, you can climb fast—but you risk falling off the cliff. With a savings account, you’re safe, but you barely move upward. With an FIA, you climb steadily, and if you slip, there’s a safety harness that prevents you from falling below where you started.
Why a Trust Beats a Will
By Chante Denis • September 24, 2025
“Thinking about estate planning? Find out why a trust is smarter than a will. Explore the advantages, from avoiding probate to protecting loved ones.”
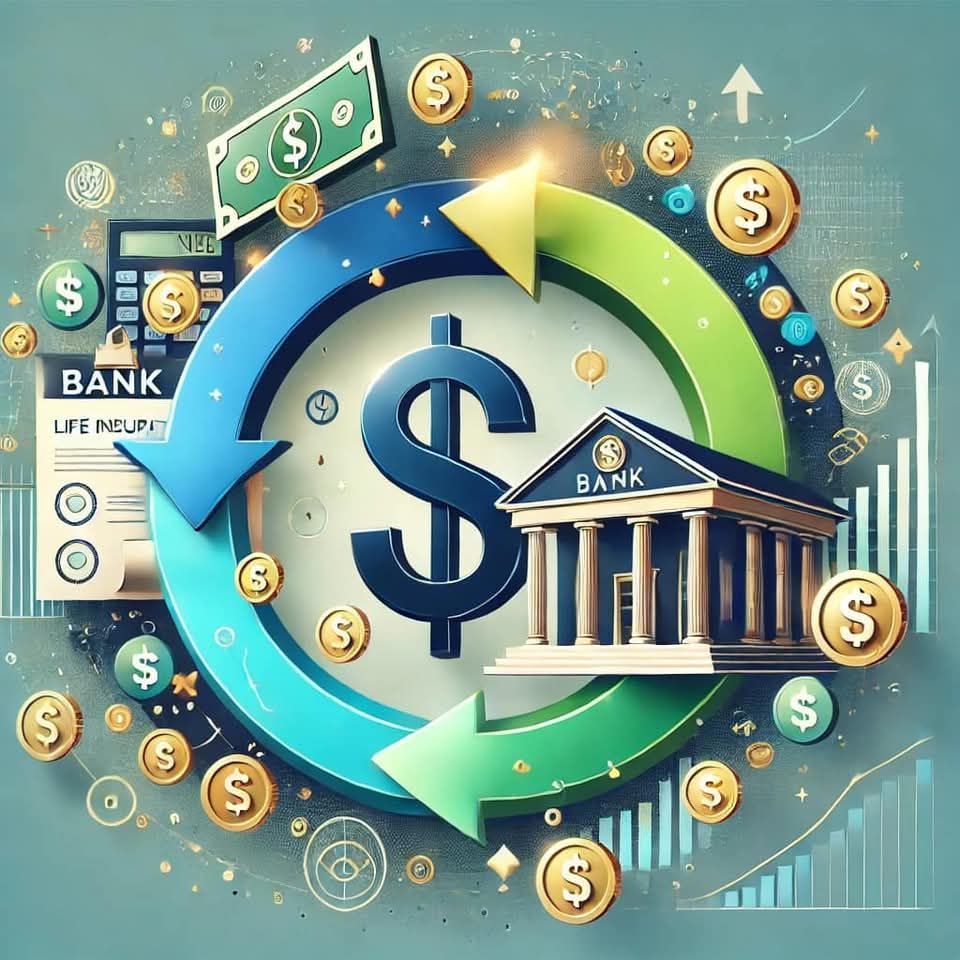
If your name is on the title, deed, or account, you’re exposed. Taxes, lawsuits, creditors
By Chante Denis • September 20, 2025
"The wealthy don’t play the same game… they play a smarter one. 💼 Own nothing. Control everything. ✅ Protect your assets from taxes, lawsuits, and creditors. ✅ Enjoy them as if they were yours. ✅ Pass them on without the headaches. Every year you wait could mean thousands lost to taxes. Learn how to structure your...
FEEL BETTER. HEAL BETTER.
By Chante Denis • September 7, 2025
Led by a Certified Cryotherapies (CCT), Glacier Chill provides both onsite and mobile cryotherapy services, bringing the benefits of cutting-edge recovery right to you. Whether you’re an athlete pushing your limits, a busy professional combating stress, or someone looking for natural pain management
Show More